Dongsung Finetec: The Korean LNG Supplier Most Global Investors Have Never Heard Of
The global LNG story is usually told through gas producers, export terminals and giant shipbuilders.
But hidden deeper in the supply chain is a Korean company making something every advanced LNG carrier depends on:
cryogenic insulation.
That company is Dongsung Finetec (KOSDAQ: 033500).
It is not a household name.
It does not produce natural gas.
And it does not build the entire ship.
But without high-performance insulation, LNG cannot be transported efficiently across the ocean.
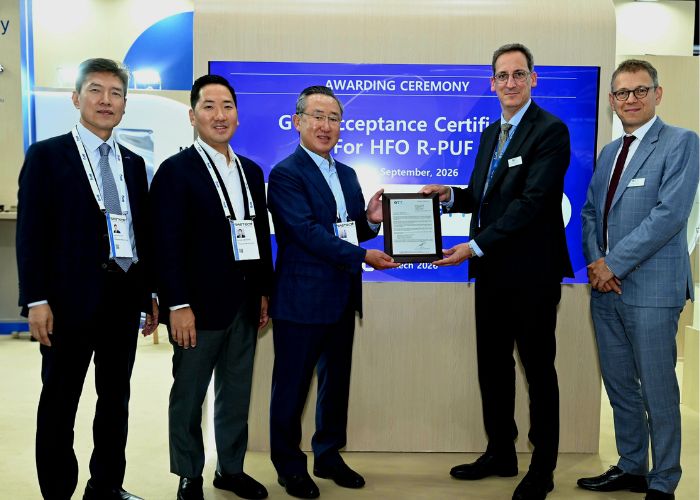
Dongsung Finetec and GTT representatives at the HFO R-PUF approval ceremony during Gastech 2026.
Source: Dongsung Finetec.
1. The Business Is Simple to Understand
LNG is natural gas cooled to approximately
-163°C.
At that temperature, natural gas becomes liquid and shrinks to roughly
1/600 of its original volume,
making long-distance transportation possible.
But maintaining that ultra-low temperature is technically demanding.
LNG carriers therefore need sophisticated cargo containment and insulation systems
to minimize heat intrusion and reduce boil-off gas losses.
Global LNG demand
↓
More LNG transportation
↓
More LNG carriers and fuel tanks
↓
More demand for cryogenic insulation
Dongsung Finetec says it supplies insulation solutions for LNG carriers,
LNG fuel tanks and LNG-related plants.
2. A Specialized Position in the LNG Supply Chain
What makes the company interesting is not simply that it participates in LNG.
It operates in a specialized area where manufacturing know-how,
approvals and long-standing relationships with the shipbuilding industry matter.
According to Dongsung Finetec,
the company is capable of producing both
insulation panels and membranes
used in LNG cargo containment systems.
The company also states that its Mark III-type LNG carrier business holds a leading global market position
and that its insulation-panel production capacity is among the largest globally.
This is not a commodity product sitting on a warehouse shelf.
It is technology embedded inside billion-dollar energy infrastructure.
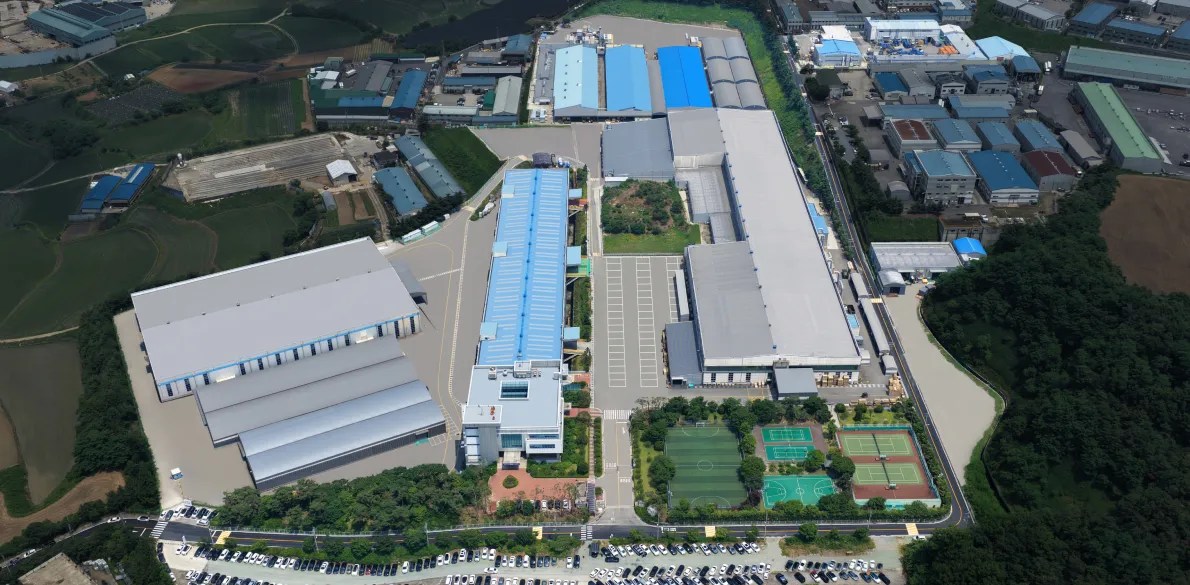
Dongsung Finetec production facilities in Anseong, South Korea.
Source: Dongsung Finetec.
3. The Financial Trend Has Been Moving in the Right Direction
The company’s recent financial trajectory deserves attention.
Consolidated revenue increased from
KRW 439.0 billion in 2022
to
KRW 597.4 billion in 2024.
Over the same period,
operating profit increased from
KRW 20.1 billion
to
KRW 54.0 billion.
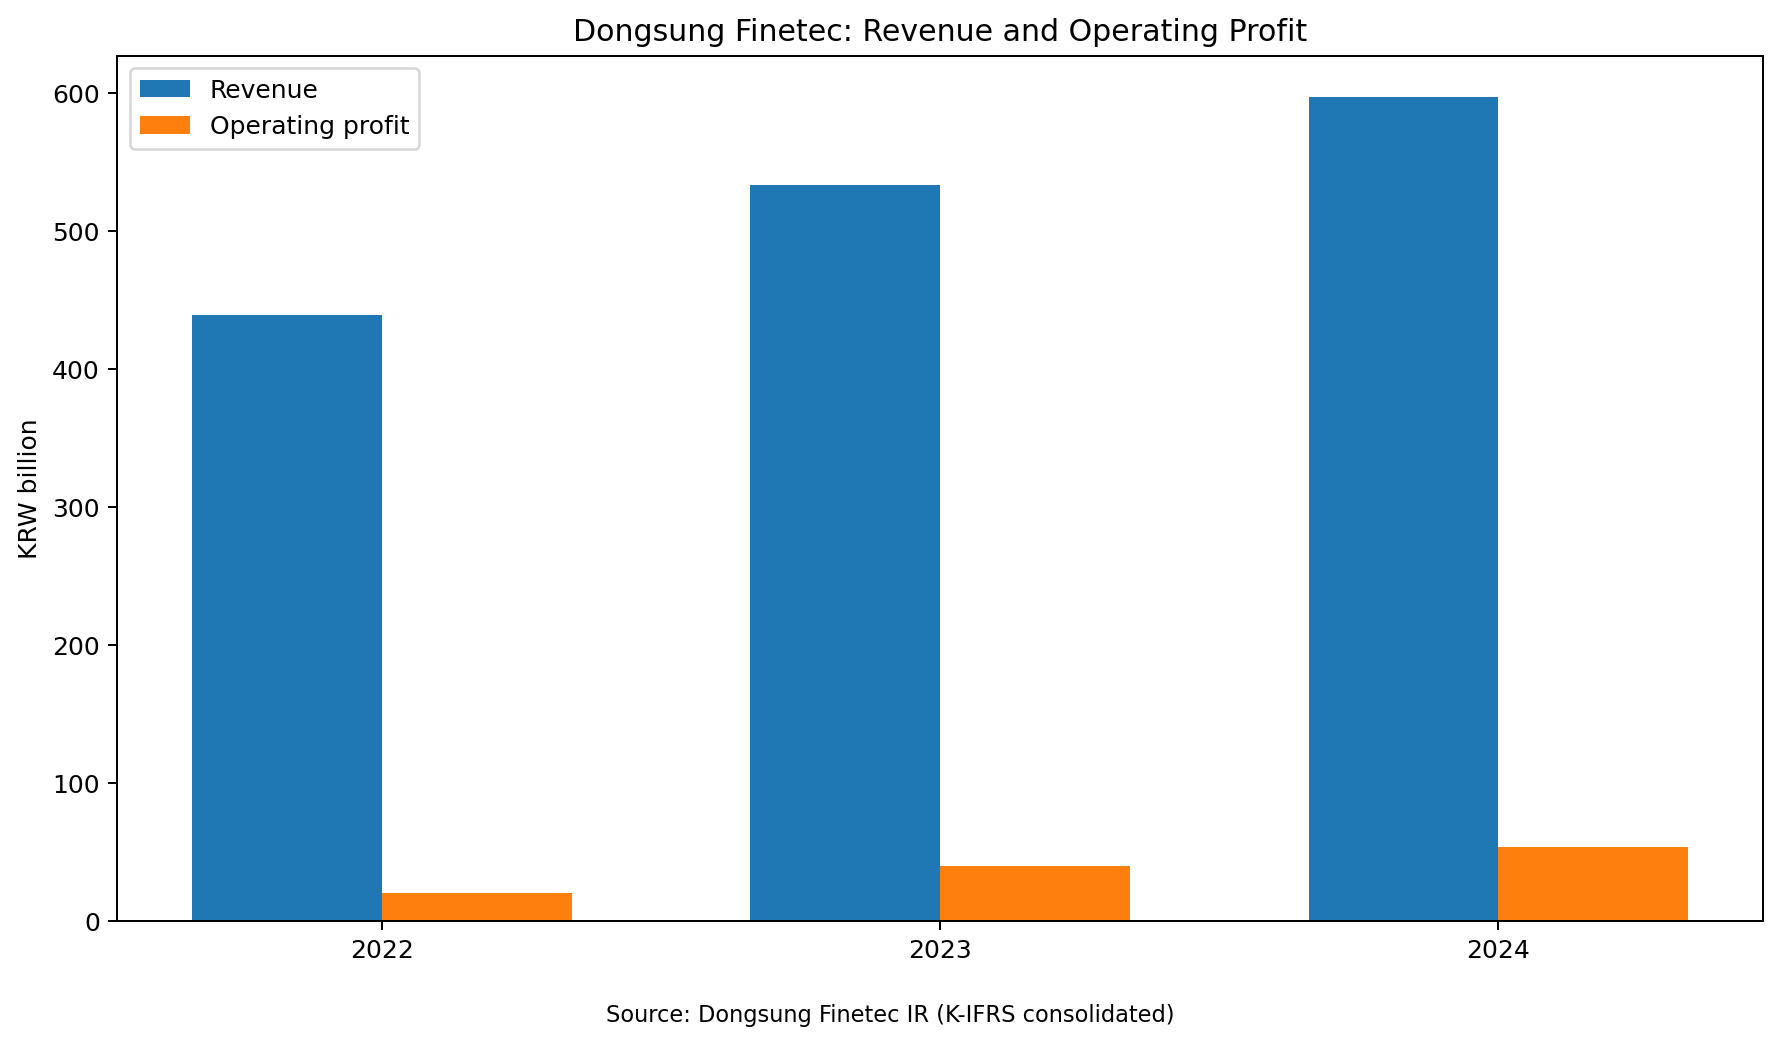
Revenue grew about 36% from 2022 to 2024.
Operating profit grew much faster.
That difference matters.
Investors generally want to see not only more sales,
but also evidence that additional revenue is translating into stronger profitability.
4. A KRW 2 Trillion Order Backlog Is Hard to Ignore
Dongsung Finetec’s own corporate history states that the company reached an
order backlog of KRW 2 trillion in 2023.
For a specialized industrial supplier,
a large backlog can be important because revenue is generally recognized
as projects progress over time.
Orders signed today
↓
Production and deliveries over time
↓
Potential future revenue visibility
Of course, backlog is not the same as guaranteed profit.
Project schedules, costs and customer timing still matter.
But it gives investors another metric to watch beyond quarterly revenue alone.
5. The Next-Generation Product May Be Even More Interesting
In September 2026,
Dongsung Finetec unveiled a new LNG carrier insulation material called
HFO R-PUF
at Gastech 2026 in Bangkok.
The product replaces conventional HFC-based blowing agents
with lower-global-warming-potential HFO alternatives.
According to the company,
DNV carbon-footprint verification showed
33% lower greenhouse-gas emissions
compared with the existing product.
Thermal conductivity was also improved by
up to 6% in certain cryogenic operating ranges.
Even more important,
the product received approval from
GTT,
the French LNG cargo-containment engineering company,
after technical verification.
Dongsung Finetec says it plans to begin applying the technology
to vessels scheduled for construction from 2027.
6. Why This Looks Like a Pick-and-Shovel LNG Play
During a gold rush,
investors sometimes prefer the company selling picks and shovels
rather than trying to guess which miner will find the most gold.
The LNG industry has a similar structure.
You could try to predict which gas producer,
exporter or shipping company will perform best.
Or you can look further down the supply chain.
Dongsung Finetec sells technology required by the infrastructure
that physically moves LNG around the world.
That does not eliminate risk.
But it gives the company exposure to a broader LNG investment cycle
rather than to the price of natural gas alone.
7. The Stock Has Recently Pulled Back
Dongsung Finetec shares have been volatile.
The stock closed at
KRW 18,360 on August 28, 2026,
before falling to
KRW 16,450 by September 21.
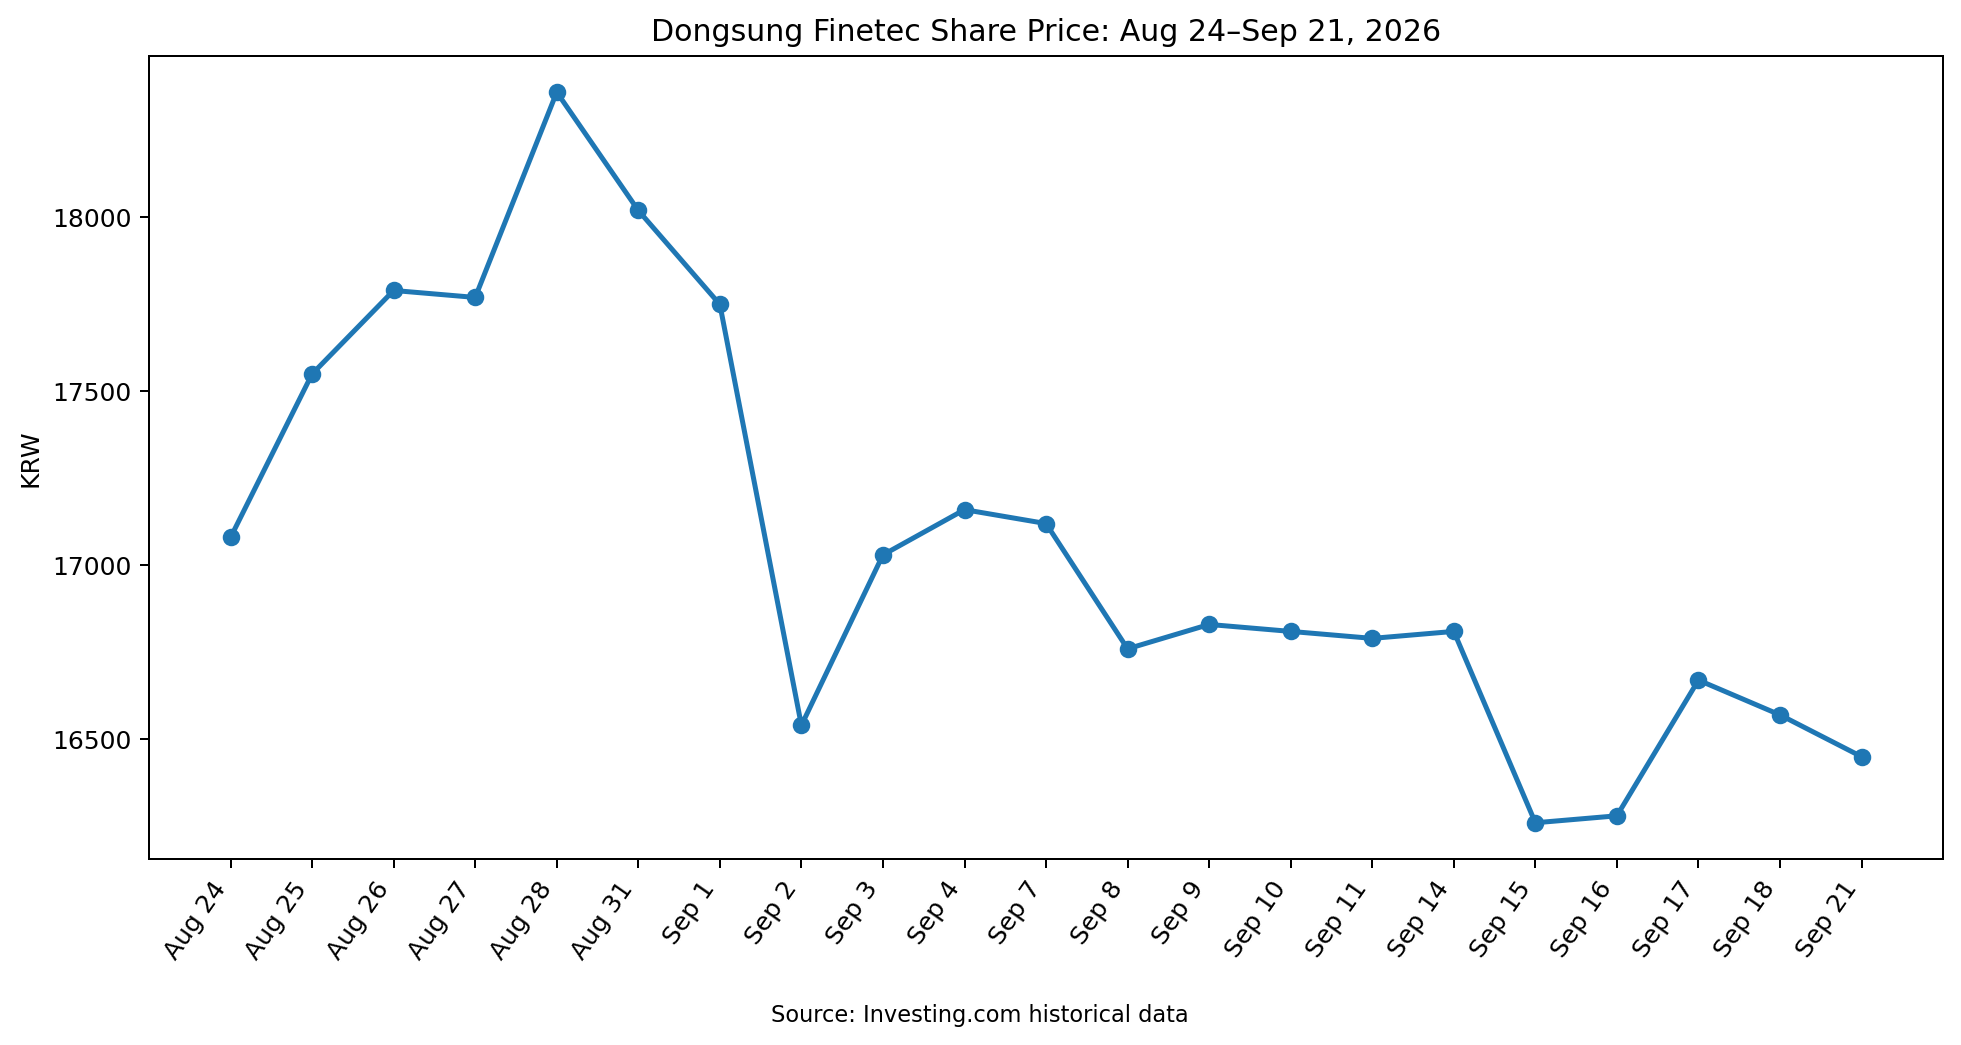
A pullback does not automatically make a stock cheap.
But when a company’s earnings trend is improving
while its share price is retreating,
it can be worth asking a simple question:
Is the business slowing down — or is the market simply becoming less enthusiastic?
That is a question investors must answer with valuation,
order trends and future earnings data.
8. Five Things Worth Watching
1. Global LNG carrier orders
A sustained vessel-order cycle would support long-term insulation demand.
2. Korean shipyard activity
Dongsung Finetec remains deeply connected to Korea’s LNG shipbuilding ecosystem.
3. Operating margins
Investors should watch whether recent profitability improvements can continue.
4. HFO R-PUF adoption
Actual vessel applications from 2027 would provide an important commercial test.
5. New energy markets
The company also highlights insulation applications in ammonia,
hydrogen and CO₂-related energy infrastructure.
9. What Could Go Wrong?
Shipbuilding is cyclical.
LNG carrier orders can slow.
Project schedules can change.
Raw-material costs can rise.
Currency movements can affect results.
The company also operates in a specialized industry where large customers
and major shipbuilding cycles can significantly influence revenue.
A good industry does not automatically mean a good stock.
A good company does not automatically mean a cheap stock.
Business quality and valuation are separate questions.
Final Thought
Dongsung Finetec is easy to overlook.
It is a Korean mid-cap industrial company operating far away
from the headlines that dominate global financial media.
Yet its products sit inside one of the most technically demanding parts
of the global LNG infrastructure chain.
It has reported rising revenue and operating profit,
a large historical order backlog,
a leading position in LNG insulation,
and a newly approved lower-carbon product aimed at future LNG carriers.
Sometimes the interesting investment story is not the company producing the energy.
It is the company quietly making the technology that allows the energy to move.
Dongsung Finetec — KOSDAQ: 033500
A specialized Korean LNG supplier
inside a much larger global energy story.
Sources: Dongsung Finetec official website, Dongsung Finetec IR,
Dongsung Finetec official news releases, and public market-price data.
Disclaimer: This article is for educational and informational purposes only.
It is not financial advice or a recommendation to buy or sell any security.
Investors should conduct their own research before making investment decisions.


Leave a comment